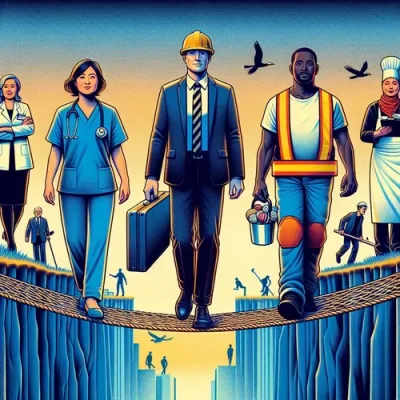
The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Income protection insurance is designed to provide financial support if you are unable to work because of illness or injury. It can help replace part of your income so you can continue meeting essential expenses while you focus on recovery.
Understanding income protection insurance
For many working Australians, income is the foundation that supports everyday life. Rent or mortgage repayments, utility bills, groceries, transport costs and other regular commitments usually depend on money continuing to come in. If an illness or injury prevents you from working, that income can stop or reduce quickly.
Income protection insurance is designed to act as a financial safety net in that situation. Rather than covering a specific medical bill or asset, it generally provides a regular benefit based on a portion of your income if you meet the policy terms and are unable to work due to illness or injury.
The purpose of this type of cover is not to remove every financial pressure, and it does not guarantee that every claim will be accepted. Instead, it can help reduce the impact of a temporary or longer-term loss of income, depending on the policy, the waiting period, the benefit period and the insurer's assessment of the claim.
Why income protection can be important
A sudden inability to work can affect more than day-to-day spending. It can place pressure on savings, increase reliance on credit or make it harder to keep up with essential household costs. Income protection insurance is intended to help provide stability during a period when earning capacity is interrupted.
For Australians who have ongoing financial obligations, the cover may help with expenses such as:
- rent or mortgage payments;
- utility bills and regular household costs;
- groceries and daily living expenses;
- transport and other necessary commitments; and
- maintaining some level of financial routine while recovering.
Government support may not be enough to cover an individual's usual living expenses. Savings can also be depleted if a period away from work lasts longer than expected. Income protection insurance can provide an additional buffer, subject to the specific policy conditions.
How much cover might a policy provide?
One of the most common questions is how much income protection cover may be needed. The answer depends on individual financial circumstances, including income, household expenses, debts, savings and other sources of support.
Many income protection policies cover up to 75% of pre-tax income. The exact amount available will depend on the insurer, the policy design and the information provided during application and underwriting.
A practical starting point is to review essential monthly expenses. This may include mortgage or rent, utilities, groceries and other necessary costs. A calculator can help you think through possible cover levels; for example, you can use the Income Protection Insurance Calculator as an educational estimate before reviewing policy details.
Any estimate should be treated as a guide only. The benefit amount that is appropriate or available will depend on the policy terms and your financial situation.
Waiting periods and benefit periods
Income protection policies usually include both a waiting period and a benefit period. These two features can strongly influence how the policy works and how much it costs.
Waiting period
The waiting period is the time you must be off work before benefits begin. The source policy examples commonly refer to waiting periods ranging from 14 days to several months. A longer waiting period may reduce premium costs, but it also means relying on savings or other resources for longer before a benefit is payable.
Benefit period
The benefit period is the maximum length of time benefits may be paid for an eligible claim. Some policies provide benefits for a set period, such as two to five years. Others may provide cover up to a specified age, often aligned with retirement. The right benefit period depends on financial needs, the type of work performed and how long income support may be required if recovery takes time.
| Policy feature |
What it means |
Why it matters |
| Benefit amount |
The portion of income the policy may replace |
Helps determine how much financial support may be available |
| Waiting period |
The time before benefits can begin |
Affects how long savings may need to cover expenses first |
| Benefit period |
The maximum time benefits may be paid |
Influences how long support may continue for an eligible claim |
Pre-existing conditions and disclosure
Some people are concerned that a pre-existing medical condition will automatically prevent them from obtaining income protection insurance. A pre-existing condition may affect the terms offered, but it does not necessarily disqualify a person from cover.
Insurers consider individual health circumstances during the application process. This may result in tailored policy terms, exclusions or other conditions. Honest disclosure is essential. Failing to disclose relevant health information can create problems later, particularly if a claim is assessed.
Tax considerations in Australia
In Australia, premiums for income protection insurance held outside superannuation can often be claimed as a tax deduction. This can affect the after-tax cost of cover, but tax outcomes depend on personal circumstances and how the policy is structured.
Because tax treatment can vary, it is sensible to speak with a qualified tax professional before relying on any deduction. You can also read more background in this guide to the tax benefits of income protection insurance in Australia.
Comparing income protection policies
Income protection policies can differ in benefit amounts, waiting periods, benefit periods, exclusions, underwriting requirements and premium structures. Comparing policies can help identify differences, but it is important to look beyond price alone.
When reviewing options, consider:
- how much of your income the policy may cover;
- how long you would need to wait before benefits begin;
- how long benefits may be payable for an eligible claim;
- how pre-existing conditions are treated;
- whether the policy terms align with essential living expenses; and
- how the policy should be reviewed if your financial situation changes.
Some people choose to seek professional assistance when navigating different policy options. An insurance broker or adviser may help explain policy features and differences; you can learn more about the role of brokers and professional assistance.
If you are ready to research available options, you can compare income protection quotes as a starting point, then review the relevant policy documents carefully before making any decision.
Reviewing cover over time
Income protection needs can change. Income, household expenses, debts, savings and family responsibilities may all shift over time. A policy that was suitable when it was first arranged may need to be reviewed later.
Regular reviews can help check whether the benefit amount, waiting period and benefit period still reflect current financial needs. A review may also be useful after a major life change, such as a change in income, a new mortgage or a change in household responsibilities.
Key takeaways
Income protection insurance is intended to help replace part of your income if illness or injury prevents you from working. For Australian adults who rely on regular earnings to meet everyday expenses, it can form part of a broader financial safety net.
The main issues to understand are how much cover may be available, how long the waiting period is, how long benefits may continue and how the policy treats health history and other conditions. It is also important to review cover over time and to seek tax or insurance guidance where appropriate.
Income protection insurance should be considered as an educational financial planning topic, not as a guaranteed solution. Whether a particular policy is appropriate depends on personal circumstances, policy terms and professional advice where needed.
Published: Thursday, 26th Dec 2024
Author: Paige Estritori


No comments yet. Be the first to share your thoughts.