Income Protection Australia :: News
SHARE

Share this news item!

Strata Storm Claim Ruling Puts Defect Exclusions in Focus

The decision underlines the importance of maintenance evidence, engineering reports and clear expectations before a loss occurs

Strata Storm Claim Ruling Puts Defect Exclusions in Focus?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

A recent Australian Financial Complaints Authority decision has highlighted a difficult but common issue for strata communities: damage that happens during a storm is not always insured storm damage.
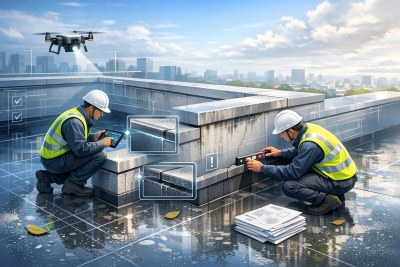
The dispute, reported on 5 November 2026, involved an owners corporation claim for a collapsed parapet wall, with the insurer declining cover on the basis that defective design, materials or workmanship were the dominant cause rather than the weather event itself.

The case is useful for strata committees because it shows how closely insurers and external experts may examine the condition and construction of a shared building element after a claim. According to the reported decision, engineering evidence pointed to an unreinforced, hollow and effectively freestanding wall, along with signs of prior cracking and movement. AFCA accepted that the storm coincided with the final collapse, but found the underlying inability of the wall to resist lateral loading was the proximate cause of the damage.

That distinction matters. Strata policies commonly respond to sudden insured events, but they usually contain exclusions for defects, gradual deterioration, wear and tear, faulty workmanship or known maintenance problems. The precise wording varies, and some policies contain exceptions for resulting damage, but the ruling is a reminder that exceptions may not restore cover for the defective item itself. This is why understanding what strata insurance does and does not cover is more than a theoretical exercise.

For owners corporations, the practical lesson is not that every defect will defeat every claim. It is that the strength of the scheme’s evidence can become critical. Committees may wish to keep clear records of building inspections, engineer reports, maintenance decisions, defect registers, repair budgets and any advice received about common property risks. Where a building element has known movement, cracking, waterproofing failure or structural concern, simply waiting until renewal or until the next storm season may create avoidable uncertainty.

The ruling also reinforces the importance of separating claim lodgement from claim expectations. A strata manager or committee should generally notify relevant damage promptly, preserve evidence and document the sequence of events, but the final outcome will depend on policy wording, causation and expert assessment. Owners who want a broader overview of process steps can revisit this guide to a strata insurance claim.

The broader message for apartment buildings and mixed-use schemes is that risk management and insurance are increasingly inseparable. A well-documented maintenance history will not guarantee cover, but it can help clarify what happened, what was known, and whether the scheme acted reasonably before the loss.

Published:Tuesday, 10th Nov 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Insurance News

Mallee Hail Is a Sharp Reminder About Harvest-Time Insurance Gaps
10 Nov 2026: Paige Estritori
A damaging hailstorm across Victoria’s Mallee has turned a promising harvest into a difficult insurance and cash-flow test for affected grain growers. ABC Rural reported on 6 November 2026 that hail swept through districts including Birchip, Wycheproof and Quambatook, damaging thousands of hectares of wheat, barley, lentils, canola and other crops just as many paddocks were ready to harvest. - read more
Strata Storm Claim Ruling Puts Defect Exclusions in Focus
10 Nov 2026: Paige Estritori
A recent Australian Financial Complaints Authority decision has highlighted a difficult but common issue for strata communities: damage that happens during a storm is not always insured storm damage. The dispute, reported on 5 November 2026, involved an owners corporation claim for a collapsed parapet wall, with the insurer declining cover on the basis that defective design, materials or workmanship were the dominant cause rather than the weather event itself. - read more
Healthcare liability pressure puts clinic renewal evidence in focus
10 Nov 2026: Paige Estritori
A new Australian healthcare professional liability market update points to a sharper divide between general insurance market conditions and the experience of healthcare organisations arranging malpractice and professional liability cover. Lockton’s 1 November 2026 update says established insurers remain selective, claims inflation is affecting attachment points and underwriters are looking more closely at how clinical governance works in practice, not merely whether accreditation exists. - read more
WA Child Safety Changes Put Fitness Compliance in the Spotlight
10 Nov 2026: Paige Estritori
Western Australia’s updated Working With Children Check laws are a timely reminder that fitness business risk is not limited to physical injury, equipment damage or venue incidents. The changes, in effect from 17 September 2026 and highlighted by AUSactive in October, mean certain adverse Working With Children outcomes from other Australian jurisdictions can now affect a person’s ability to work with children in WA. - read more


Life Insurance Articles

Does Income Protection Insurance Cover Redundancy or Job Loss?
Income protection insurance is generally designed to help replace part of your income if illness or injury leaves you unable to work. It usually does not cover redundancy, ordinary job loss, business downturn or reduced hours for non-medical reasons, although some policies may respond if illness or injury reduces your work capacity. - read more
A Guide to Income Protection Insurance in Australia
Income protection insurance can help replace part of your income if illness or injury prevents you from working. This guide explains how Australian income protection policies work, what to compare, how claims are assessed, and the tax and policy details to understand before choosing cover. - read more
The Essential Guide to Calculating Your Income Insurance Coverage
Income protection insurance is a type of policy designed to provide you with a financial safety net in the event that you are unable to work due to illness or injury. Its core purpose is to replace a portion of your income, helping you to maintain your standard of living until you're able to return to work. It's an essential consideration for anyone who relies on their income to support themselves and their families. - read more
Income Protection for Employees in Australia: Sick Leave, Workers Compensation and Super Cover
Australian employees may already have sick leave, workers compensation rights or insurance through superannuation, but those protections do not always cover the same risks as personal income protection insurance. This guide explains how they can work together and what employees should check before comparing cover. - read more

Knowledgebase
Depreciation:
The reduction in the value of an asset over time, used in insurance to calculate the actual cash value of property.